You check your payslip in February 2026 and notice that something’s missing. Hey, just a heads-up that a small part of your gross pay has been taken out under a line item called “MyFutureFund”.
You didn’t sign up for this, did you? You didn’t fill out a form. It just happened.
Welcome to auto-enrolment! From 1 January 2026, the Irish government started pushing hundreds of thousands of workers into a new state-backed retirement savings scheme. If you weren’t already paying into a pension through your payroll, you were in. No application. There’s no way around it. Just a deduction .
Let’s be real. A lot of people get annoyed by this. It feels like a pay cut. Whether this is a good deal or a bad deal depends on your salary and whether you already have a better option sitting in your desk drawer.
The mechanics: where your money actually goes
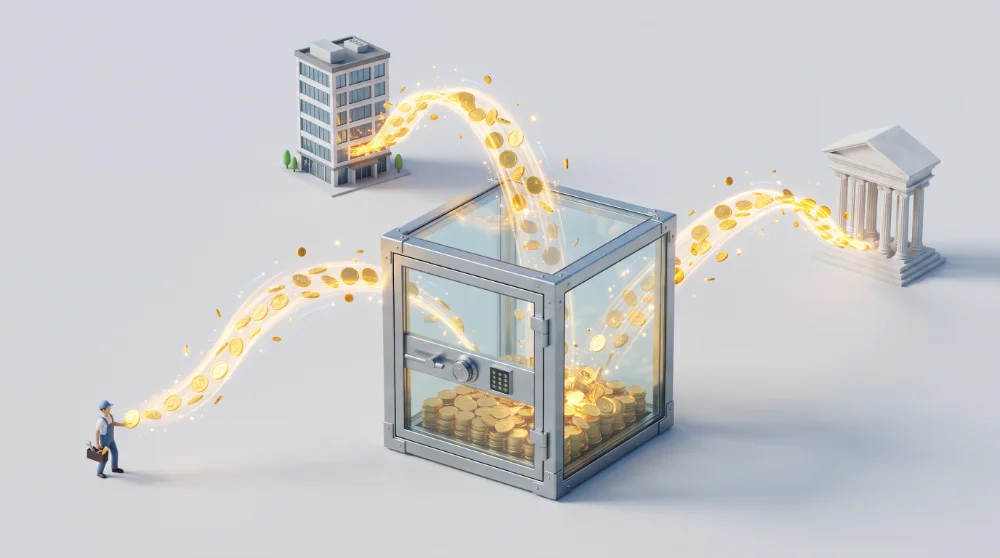
Here’s the lowdown. You put in 1.5% of your gross salary. Your employer matches that 1.5%. The State puts in another 0.5%. Total going into your pot: 3.5% .
So, for every three euros you put in, your employer puts in three more, and the government chimes in with an extra euro. That means you’ve got seven euros for your trouble. On paper, that seems like a 133% return on your investment right away. You won’t find that anywhere else.
But there’s a catch, and it’s a big one for anyone on a decent salary.
The tax relief trap for higher earners
This is where things get interesting, but be warned, most articles will give you a headache with jargon.
If you’re a higher-rate taxpayer (earning over €40,000), the standard private pension system gives you tax relief at 40%. So, for every €100 you put into a private pension, you only pay €60 in take-home pay. The government ends up paying the other €40 through the tax system.
MyFutureFund doesn’t work like that. It uses a flat top-up. The state gives you back 25% of what you put in. If you’re earning more, this isn’t as good a deal as the 40% relief you’d get with a private scheme.
You might think the employer contribution makes up for it. Sometimes it does. Sometimes it doesn’t. If your employer already offers a decent private pension with 6% or 8% matching, staying in MyFutureFund is almost certainly leaving money on the table.
But for someone on a lower salary, the story changes. If you’re a standard-rate taxpayer, you get 20% relief on a private pension. MyFutureFund gives them an effective 25% top-up. If that’s the case, it looks like the state scheme is actually better than the private option.
The system isn’t all good or all bad. It depends on your payslip.
If you are still confused about how the government top-up actually compares to standard tax relief, watch this breakdown. It explains the mechanics of the “3-3-1” contribution matching and, crucially, why anyone on the higher rate of tax might actually be losing out by staying in the State scheme.
Who gets swept in (and who can walk away)
You are automatically enrolled if you are aged between 23 and 60, earn €20,000 or more per year across all employments, and are not already contributing to a pension through your payroll .
If you are outside that bracket, you can opt in voluntarily. If you are already in a workplace pension, you are exempt. The system checks your payslip data through Revenue, so it knows who is already saving .
Here is the part that matters for anyone who is unhappy about the deduction. You cannot leave immediately. You must stay in for six months. After that, you have a two-month window to opt out and get your own contributions refunded . If you miss that window, you can pause your contributions, but the money already in the pot stays there until you retire.
Worth keeping in mind: if you opt out and later become eligible again, you will be automatically re-enrolled after two years. The system is designed to be sticky .
The employer problem nobody wants to talk about
Some employers are not being fair. The Department of Social Protection has already warned about cases where businesses are telling their staff that they must sign up to an employer-sponsored scheme before the end of 2026, or that the law has changed to make them do so.
That’s not true. There’s no legal obligation for workers to join an employer-sponsored pension scheme. And it’s not cool for an employer to stop an employee from getting involved with MyFutureFund. You could be fined or even go to prison.
If your boss is pushing you towards a private scheme with high fees and poor matching, ask questions. Make sure you ask for it in writing. Then check the terms against what MyFutureFund offers. The state scheme isn’t perfect, but it’s transparent, and the fees are capped at a low level.
The eight-month reality check
By now, if you were enrolled on 1 January, you are past the initial adjustment. You have seen the deduction. You have maybe logged into the portal once, got confused by the investment options (low, medium, or high risk), and closed the tab.
The real decision point is approaching. The opt-out window opens in July 2026 and closes in August. After that, you are in for the long haul, at least until you pause contributions or change jobs .
Seasoned savers know that the worst thing you can do is nothing. If you are on a good salary with a decent company pension, you should almost certainly opt out of MyFutureFund and stick with your existing arrangement. The tax relief is better, the investment options are wider, and you keep control.
If you are on a lower salary, or your employer does not offer any pension at all, MyFutureFund is probably the best deal you are going to get. The State top-up beats standard-rate tax relief, and the pot follows you from job to job with no paperwork .
The bottom line
MyFutureFund is not a scam. It is not a conspiracy. It is a blunt instrument designed to solve a real problem: too many Irish workers were heading toward retirement with nothing but the State pension, which is roughly €15,000 a year .
But it is not a one-size-fits-all solution. The higher your salary, the less attractive it becomes. The lower your salary, the more the State top-up matters.
You have a window to decide. Use it. Look at your payslip. Look at what your employer offers. Do the sums.
Because in 2026, the story of your retirement is being written whether you pay attention or not. The only question is who holds the pen.